Powerica Ltd IPO Analysis
 By Admin
|
Mar 21, 2026
|
1 min read
|
114
|
🤍
0
What Does Powerica Do?
Powerica Limited is an integrated power solutions provider established in 1984, specialising in diesel generator sets (DG sets) for both primary and standby power applications. The company is one of the original equipment manufacturers (OEMs) for Cummins India, manufacturing generator sets across a comprehensive range from 7.5 kVA to 10,000 kVA. It also offers medium speed large generators (MSLG) in collaboration with HD Hyundai Heavy Industries. Powerica expanded into renewable energy in 2008 as an independent power producer and now operates 11 wind power projects in Gujarat with a total installed capacity of 279.55 MW.
IPO Snapshot
| Company Name | Powerica Limited |
|---|---|
| Sector / Industry | Power Solutions · Capital Goods · Renewable Energy |
| Founded | 1984 (Generator Sets Business) |
| Headquarters | 9th Floor, Bakhtawar, Nariman Point, Mumbai – 400 021 |
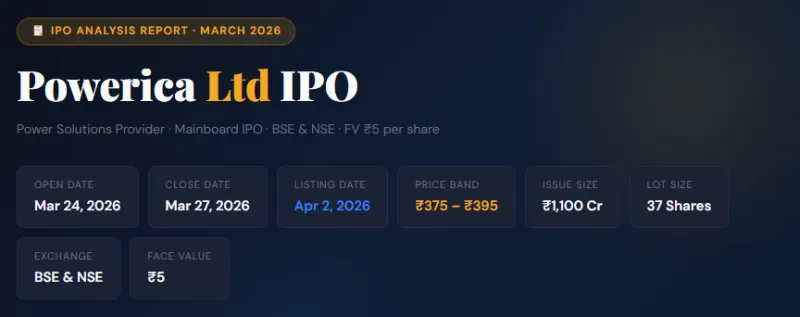
| Issue Size | ₹1,100 Crore |
| Fresh Issue | ₹700 Crore (17.72 million shares) |
| Offer for Sale (OFS) | ₹400 Crore (10.13 million shares) |
| Market Cap (Post-Listing Est.) | ~₹5,000 Crore (at upper band) |
| Pre-IPO Promoter Holding | 100% (Oberoi Family & Family Trusts) |
| Retail Quota | 35% |
| QIB Quota | 50% |
| NII / HNI Quota | 15% |
| Registrar | MUFG Intime India Pvt. Ltd. |
| Book Running Lead Managers | ICICI Securities, IIFL Capital Services, Nuvama Wealth Management |
| Allotment Date | March 30, 2026 |
| Anchor Bidding Date | March 23, 2026 |
Business Overview
Revenue Segments
- Generator Set Business (80.5%+ of revenue): Low HP (7.5–160 kVA), Medium HP (180–500 kVA), and High HP (above 500 kVA) powered by Cummins engines
- Wind Power Business (~15–19.5% of revenue): 11 wind projects in Gujarat, 279.55 MW installed capacity; also provides EPC & O&M services
- MSLG Products: Medium speed large generators up to 10,000 kVA in collaboration with HD Hyundai Heavy Industries
- Emission Control (Associate Co.): Retrofit emission control devices via Platino Automotive
Industry Position & Key Advantages
- 40+ year OEM partnership with Cummins India – one of the longest-standing relationships in the DG set industry
- Three manufacturing facilities in Bengaluru, Silvassa & Khopoli
- Growing data centre demand driving DG set orders (currently 12–13% of revenue, expected to reach ~15%)
- Diversified across conventional power and renewable energy infrastructure
- Second attempt at listing (previously filed in 2019); signifies management's confidence in current market
Financial Performance
| Metric | FY 2023 | FY 2024 | FY 2025 | H1 FY2026 (Sep'25) |
|---|---|---|---|---|
| Revenue from Operations (₹ Cr) | ~₹1,900 | ₹2,356.77 | ₹2,710.93 | ₹1,447.44 |
| Net Profit / PAT (₹ Cr) | ~₹180 | ₹226.11 | ₹175.83 | ₹129.00 |
| EBITDA (₹ Cr, Est.) | ~₹260 | ~₹340 | ~₹300 | ~₹180 |
| Total Debt (₹ Cr) | – | – | ~₹1,013 (Jul'25) | ₹1,214.25 (Feb'26) |
| Other Income (₹ Cr) | – | ₹146.8 | ₹57.7 | – |
Revenue CAGR (FY23–FY25 Est.)
~19.4%
Strong top-line momentum
PAT FY24→FY25 Change
-22.2%
Impacted by lower other income
H1 FY26 Annualised PAT (Est.)
~₹258 Cr
Recovery trajectory visible
Margin & Profitability Analysis
Revenue grew at a healthy 19–20% CAGR over FY23–FY25, reflecting strong demand for DG sets from infrastructure, industrial, and data centre customers. However, net profit declined 22% in FY25 primarily due to a sharp drop in other income from ₹146.8 Cr (FY24) to ₹57.7 Cr (FY25). Operationally, the core business remained stable. H1 FY26 performance (PAT of ₹129 Cr on revenues of ₹1,447 Cr) suggests a recovery trend, with annualised PAT of ~₹258 Cr implying a significant rebound vs FY25's ₹175.83 Cr.
Key Financial Ratios
| Ratio | Value | Industry Benchmark | Signal |
|---|---|---|---|
| P/E Ratio (IPO, at upper band) | ~28–30x (FY25 basis) | 25–35x (Power Equipment) | Neutral |
| P/E Ratio (H1 FY26 annualised) | ~19–20x | 25–35x (Power Equipment) | Attractive |
| ROE (Return on Equity) | 14.52% | 15–20% (Sector) | Moderate |
| ROCE (Return on Capital Employed) | 20.35% | 18–25% (Sector) | Strong |
| Debt / Equity Ratio | 0.28x (pre-IPO); ~0x (post-IPO target) | <1x (Healthy) | Manageable |
| P/B Ratio (at upper band, est.) | ~3.5–4x | 3–6x (Sector) | Neutral |
| Operating Margin (est.) | ~10–12% | 10–15% (Sector) | Moderate |
| Net Profit Margin (FY25) | ~6.5% | 8–12% (Sector) | Below Avg |
| Post-IPO Debt Position | Near Zero (₹525 Cr to be repaid) | – | Bullish |
Valuation Analysis
IPO Valuation Assessment
At the upper price band of ₹395 per share, Powerica's post-issue market capitalisation stands at approximately ₹5,000 crore. On trailing FY25 earnings (PAT ~₹175.83 Cr), the P/E works out to roughly 28–30x — moderate for an industrial/power company. However, when valued on H1 FY26 annualised PAT (~₹258 Cr), the implied P/E drops to a more attractive 19–20x, suggesting the current band prices in a recovery rather than peak earnings. The near-zero debt position post-IPO significantly improves the future earnings quality. The planned ₹525 crore debt repayment will reduce interest costs and directly enhance net margins from FY27 onwards.
| Company | Market Cap (₹ Cr) | P/E Ratio | ROE (%) | Revenue (₹ Cr) | Segment |
|---|---|---|---|---|---|
| Powerica Ltd IPO | ~5,000 | ~20–30x | 14.52% | 2,711 | DG Sets + Wind |
| Cummins India Ltd | ~60,000+ | ~40–50x | ~25% | ~9,800 | Engines & Power |
| Greaves Cotton Ltd | ~3,500–4,000 | ~25–35x | ~8–10% | ~2,200 | Engines, EV |
| Kirloskar Electric | ~2,500–3,000 | ~20–28x | ~12% | ~1,500 | Industrial Motors |
| KOEL (Kirloskar Oil Engines) | ~8,000–10,000 | ~20–25x | ~18% | ~4,500 | Engines & DG Sets |
Strengths & Growth Drivers
- 40+ Year Cummins OEM Partnership: Powerica is one of Cummins India's longest-serving OEMs, conferring exclusive product access, technical knowledge, and strong credibility in the DG set market
- Data Centre Demand Surge: India's rapidly growing data centre sector requires uninterrupted power supply; Powerica's management highlights this as the fastest-growing demand vertical, currently at 12–13% of revenue with strong order book expansion
- Diversified Revenue Base: Generator sets (~80%) + wind power (~15–19%) provides resilience across economic cycles; wind power assets generate recurring revenue
- Comprehensive Product Range: Capacity from 7.5 kVA to 10,000 kVA covers retail, commercial, industrial, and utility segments — widest in its category in India
- Zero-Debt Target Post-IPO: ₹525 Cr earmarked for debt repayment will transform the balance sheet, reduce interest burden by ~₹70–100 Cr annually, and significantly improve net margins from FY27
- Three Manufacturing Facilities: Pan-India manufacturing presence across Bengaluru, Silvassa, and Khopoli reduces supply chain concentration risk
- Wind Power as Renewable Play: 279.55 MW operational wind capacity in Gujarat positions the company as a credible play on India's energy transition
- GE Alliance for Wind Projects: Strategic collaboration with GE for new wind project development leverages global technical expertise
- Infrastructure & Industrial Tailwinds: India's infrastructure push (highways, airports, metros) and industrial capex cycle benefits DG set demand
Risk Factors
- Revenue Concentration in DG Sets (~80%): Any disruption to the Cummins partnership, engine supply, or adverse regulatory changes for diesel generators could materially impact operations
- FY25 Profit Decline: Net profit fell 22% YoY in FY25 despite 15% revenue growth, highlighting sensitivity to non-operating income fluctuations and raising concerns about earnings quality
- High Debt Pre-IPO: Outstanding borrowings of ₹1,214 Cr (Feb 2026) create refinancing risk; IPO proceeds will help, but full deleveraging depends on execution
- Renewable Energy Disruption: Long-term adoption of solar, battery storage, and grid improvements may reduce demand for diesel-based backup power, threatening the core DG set business
- Dependence on Cummins India: The company relies on Cummins for engines and alternators; any pricing, supply, or partnership changes could impact margins and product availability
- Cyclicality of Industrial Demand: DG set sales are highly correlated with industrial capital expenditure cycles, infrastructure investment, and construction activity — all cyclical in nature
- OFS Component (₹400 Cr): Promoter sell-down through OFS means a portion of IPO proceeds does not flow into the business — a negative signal for some investors
- Regulatory & Environmental Risks: Tightening emission norms for diesel generators (BS-VI standards and beyond) may require significant product/manufacturing upgrades
- Second IPO Attempt: Having shelved a 2019 IPO plan adds reputational/market timing risk perception among institutional investors
- Wind Power Execution Risk: EPC and O&M services in wind power carry project execution and counter-party risks
IPO Subscription Data
📌 IPO opens March 24, 2026 and closes March 27, 2026. Subscription data will be live updated on NSE/BSE during the bidding period. Data below reflects expected structure.
| Category | Shares Reserved | Quota | Min Investment | Subscription Status |
|---|---|---|---|---|
| Retail Individual Investors (RII) | 35% of issue | 35% | ₹14,615 (1 lot × 37 shares) | Awaiting |
| Qualified Institutional Buyers (QIB) | 50% of issue | 50% | Institutional | Awaiting |
| Non-Institutional Investors (NII / HNI) | 15% of issue | 15% | ₹2,04,610 (sNII, 14 lots) | Awaiting |
| Total Issue | 2,78,48,100 shares | 100% | – | Opens Mar 24 |
Grey Market Premium (GMP)
| Parameter | Value |
|---|---|
| IPO Price (Upper Band) | ₹395 |
| Grey Market Premium (GMP) as of Mar 21, 2026 | ₹8 – ₹13 per share |
| Estimated Listing Price (GMP basis) | ₹403 – ₹408 |
| Estimated Listing Gain % (GMP basis) | ~2% – 3.3% |
| GMP Trend | Flat / Tepid (₹0 on Mar 18 → ₹13 on Mar 19 → ₹8 on Mar 21) |
| Kostak Rate | Not established / ₹0 |
⚠️ GMP is an unofficial grey market indicator and does not guarantee actual listing price. GMP can change significantly based on market conditions, subscription levels, and sector sentiment. Do not make investment decisions solely based on GMP.
Objects of the Issue
| Purpose | Amount (₹ Cr) | % of Fresh Issue | Remarks |
|---|---|---|---|
| Repayment / Prepayment of Borrowings | ₹525 Crore | 75% | Primary Use |
| General Corporate Purposes | Balance (~₹175 Cr) | ~25% | Secondary Use |
| Offer for Sale (OFS – Promoter Exit) | ₹400 Crore | N/A (not to company) | Promoter Liquidity |
The primary objective of Powerica's IPO is to transform itself into a zero-debt company. As of February 2026, total outstanding bank borrowings stood at ₹1,214.25 crore. The company plans to repay ₹525 crore using fresh issue proceeds, with Chairman & MD Bharat Oberoi confirming this will provide greater financial flexibility for future expansion. Notably, data centre-driven DG set demand is the identified next growth vector requiring capital flexibility.
Final Summary
Business Quality: Powerica is a well-established, 40-year-old business with proven execution in the DG set segment and a growing renewable energy portfolio. The Cummins OEM partnership provides technological differentiation, while the 279.55 MW wind power business adds recurring, inflation-linked revenue. The data centre tailwind is a meaningful and credible demand driver that could sustain double-digit revenue growth over the next 3–5 years.
Financial Strength: Revenue growth has been strong (~19–20% CAGR), and ROCE of 20.35% indicates efficient capital utilisation. However, FY25 showed profit volatility — the 22% PAT decline, while driven by non-recurring factors (lower other income), raises questions about earnings predictability. The high debt (₹1,214 Cr) is the most significant financial risk pre-IPO. Post-IPO debt repayment should materially improve net margins. H1 FY26 results (PAT ₹129 Cr) suggest the business is already recovering.
Valuation: At ₹395 per share (upper band), the ~₹5,000 Cr market cap implies 28–30x P/E on trailing FY25 earnings. This is moderate — not cheap, but not stretched for a company with strong revenue CAGR and an improving financial structure post-deleveraging. On a forward basis (annualised H1 FY26), valuation drops to a more attractive ~19–20x P/E. The OFS component of ₹400 Cr (promoter exit) is a mild negative, but the focus on debt reduction through fresh issue proceeds is a positive capital allocation signal.
Listing Probability Analysis
Listing Assessment Framework
- GMP Trend: Started at ₹0 on Mar 18, peaked at ₹13 on Mar 19, stabilised at ₹8–₹13 as of Mar 21. Tepid grey market activity suggests limited speculative excitement but also no negative sentiment
- Sector Momentum: Power and capital goods sector is in a structural upcycle in India, backed by data centres, infrastructure, and industrial capex — positive for long-term investors
- Market Conditions: Overall market sentiment in late March 2026 will be key; Nifty direction in the days preceding listing will significantly influence opening price
- QIB Response: Anchor investor participation (March 23) and QIB subscription will be critical signals — strong QIB interest historically translates to positive listing
- Valuation Buffer: At 19–20x forward P/E post-deleveraging, there is room for re-rating if the company demonstrates consistent profit growth from FY27 onwards
Sources & References
- Powerica Ltd Red Herring Prospectus (RHP) – Filed with SEBI / ROC, March 2026
- Powerica Ltd Draft Red Herring Prospectus (DRHP) – Filed with SEBI, August 2025
- NSE India – IPO Subscription & Bidding Data (www.nseindia.com)
- BSE India – Listing & Corporate Filings (www.bseindia.com)
- Business Standard – "Powerica sets IPO price band at ₹375–395" (March 18, 2026)
- BusinessToday – "Powerica IPO to open on March 24" (March 18, 2026)
- PTI / FreePressJournal – "Powerica Launches ₹1,100 Crore IPO on March 24" (March 18, 2026)
- IPOWatch.in – Powerica IPO GMP & Subscription Analysis
- Chittorgarh.com – Powerica IPO Date, Price, GMP, Review & Analysis
- CapMint.com – Powerica Ltd Financial Ratios (ROE, ROCE, D/E)
- Chanakyanipothi.com – Powerica IPO Analysis & GMP Updates
- AngelOne.in – Powerica IPO DRHP Analysis (August 2025)
- Multibagg.ai – "Powerica IPO: Aims for Zero Debt with ₹1,100 Crore Issue"
Financial & Regulatory Disclaimer
InvesTalks provides stock market analysis, equity research, and financial content strictly for educational and informational purposes only. We are not a SEBI-registered investment advisor or portfolio manager. Market investments are subject to market risks. Always perform your own research or consult a certified SEBI-registered financial advisor before making buy/sell decisions.
CMPDI — A Coal India Subsidiary · Mining Consultancy & Engin...
NEXTNIFTY 50 Market Analysis – 24 March 2026
Admin
Equity Research & Financial AnalysisCurated by the InvesTalks financial analysis team. Dedicated to providing disciplined stock market insights, technical chart evaluations, and long-term investor education.
 Market News & Outlook
Login to comment.