Index
- Introduction
- IPO Snapshot
- REVENUE SEGMENTS
- KEY CLIENTS & CUSTOMER CONCENTRATION
- INFRASTRUCTURE & SCALE
- FINANCIAL PERFORMANCE
- FINANCIAL TREND ANALYSIS
- KEY FINANCIAL RATIOS
- VALUATION ANALYSIS & PEER COMPARISON
- KEY STRENGTHS
- KEY RISKS
- IPO SUBSCRIPTION DATA (Day 1)
- GRAY MARKET PREMIUM (GMP)
- OBJECTS OF THE ISSUE
- FINAL SUMMARY
- LISTING PROBABILITY ANALYSIS
- SOURCES & REFERENCES
- KEY DATES
- Gallery
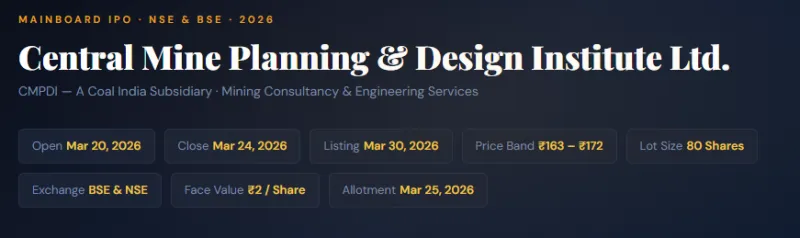
CMPDI — A Coal India Subsidiary · Mining Consultancy & Engineering Services
 By Admin
|
Mar 21, 2026
|
1 min read
|
199
|
🤍
0
Central Mine Planning & Design Institute Limited (CMPDI) is India's foremost mining consultancy and engineering services company, set up in 1974 as a wholly-owned subsidiary of Coal India Limited (CIL) — the world's largest coal producer. Headquartered in Ranchi, Jharkhand, CMPDI provides end-to-end technical consultancy across the entire value chain of coal and mineral resource development.
IPO Snapshot
| Company Name | Central Mine Planning & Design Institute Limited (CMPDI) |
|---|---|
| Sector | Mining Consultancy & Engineering Services |
| Industry | PSU / Government — Coal & Minerals |
| Established | 1974 (incorporated as Coal India subsidiary in 1975) |
| Headquarters | Gondwana Place, Kanke Road, Ranchi, Jharkhand |
| Promoter | Coal India Limited (Govt. of India Enterprise) |
| Issue Size | ₹1,842.12 Crore |
| Fresh Issue | Nil (100% Offer for Sale) |
| Offer for Sale | 10,71,00,000 equity shares |
| Market Cap After Listing | ~₹12,280 Crore |
| Promoter Holding (Pre-IPO) | 100% |
| Promoter Holding (Post-IPO) | ~85% |
| Retail Quota (RII) | 35% — 3,74,85,000 shares |
| QIB Quota | 50% — 5,35,50,000 shares |
| NII / HNI Quota | 15% — 1,60,65,000 shares |
| Employee Reservation | 53,55,000 shares |
| Shareholder Quota (Coal India) | 1,07,10,000 shares |
| Book Running Lead Managers | IDBI Capital Markets & Securities Ltd; SBI Capital Markets Ltd |
| Registrar | KFin Technologies Ltd |
| Anchor Investors Round | ₹469.74 Cr from 22 anchors (Mar 18, 2026) |
| Key Anchor Investors | LIC, Nippon India MF, ICICI Prudential MF, Edelweiss MF, Goldman Sachs, Citigroup, BNP Paribas, GIC, Societe Generale |
| Status | Mini Ratna Category-I PSU |
REVENUE SEGMENTS
| Business Vertical | Revenue Share (FY25) |
|---|---|
| Geological Exploration & Resource Evaluation | 46.2% |
| Mine Planning & Design Services | ~25% |
| Environmental Planning & Monitoring Services | ~15% |
| Geomatics, Remote Sensing & Survey Services | ~14% |
KEY CLIENTS & CUSTOMER CONCENTRATION
CMPDI's revenue is heavily concentrated among government entities. Coal India Limited and its subsidiaries contributed 67.1% of revenue in FY2025 (down from 80.2% in FY2024, showing early signs of diversification). Government entities/agencies as a whole account for ~97.8% of total revenues. The top 10 clients cumulatively contribute approximately 95% of revenues.
INFRASTRUCTURE & SCALE
- One of India's largest fleets of exploratory drilling equipment for coal & mineral exploration (as of March 31, 2025).
- Seven Regional Institutes across coal-producing states — Madhya Pradesh, Chhattisgarh, Odisha, and West Bengal.
- Eight advanced testing laboratories spread across coalfields in India.
- Capability to plan open-cast mines with annual production up to 85 million tonnes; mining depths up to 420 metres.
- Active participation in NMET-funded drilling and exploration for non-coal minerals (bauxite, copper, zinc, magnetite, and more).
FINANCIAL PERFORMANCE
| Metric | FY2023 | FY2024 | FY2025 | 9M FY26* |
|---|---|---|---|---|
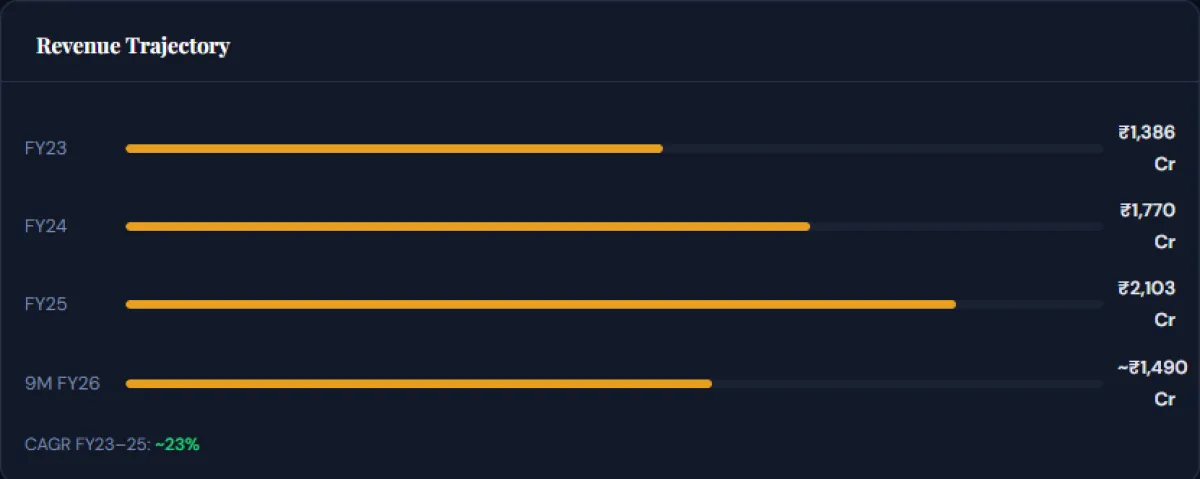
| Revenue from Operations (₹ Cr) | 1,386.1 | 1,770.2 | 2,102.8 | ~1,490 |
| Total Revenue incl. Other Income (₹ Cr) | — | 1,770.2 | 2,177.5 | — |
| EBITDA (₹ Cr) | ~580 | ~760 | ~900+ | — |
| EBITDA Margin | ~42% | ~43% | >42% | — |
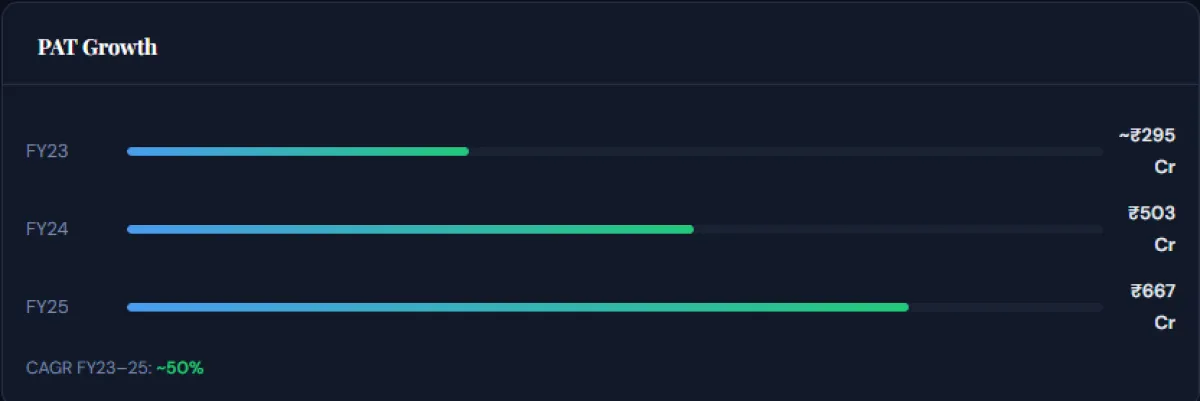
| Net Profit / PAT (₹ Cr) | ~295 | 503.2 | 666.9 | — |
| EPS (₹) | ~4.2 | ~7.1 | 9.3 | — |
| Total Debt (₹ Cr) | Nil | Nil | Nil | Nil |
| Net Worth (₹ Cr) | — | ~1,400 | ~1,820 | — |
* 9M FY26 refers to the nine months ended December 31, 2025. Exact EBITDA figures are estimated based on reported operating margins. Source: Company RHP, IPOWatch, JM Financial.
FINANCIAL TREND ANALYSIS
- Revenue CAGR of ~23%from ₹1,386 crore (FY23) to ₹2,103 crore (FY25) reflects strong demand for mining consultancy driven by India's energy security push.
- PAT grew ~50% CAGR(FY23–25), from ~₹295 crore to ₹667 crore — significantly outpacing revenue growth, reflecting strong operational leverage.
- Margins above 40% consistently— rare for a PSU and comparable to top-tier IT services companies.
- Completelydebt-freebalance sheet as of December 31, 2025 — zero borrowings.
- Dividend-paying PSU following Ministry of Finance dividend guidelines.
KEY FINANCIAL RATIOS
| Ratio / Metric | Value | Signal |
|---|---|---|
| P/E Ratio (IPO — Upper Band) | ~18.5× | Strong (Discount to Peers) |
| Industry Peer Avg P/E | 22.6× | Reference |
| Price / Book (P/B) Ratio | ~6.7× | Neutral |
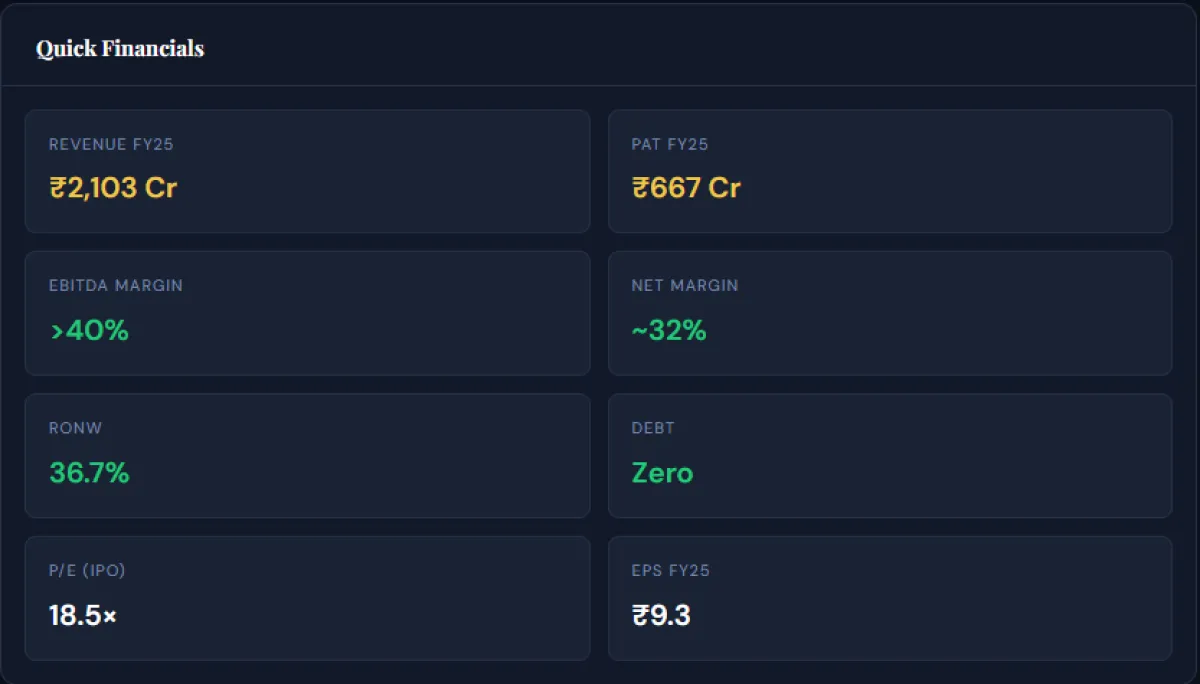
| ROE / RoNW (FY25) | 36.7% | Strong |
| Weighted Avg. RoNW | 34.8% | Strong |
| ROCE | >35% | Strong |
| Debt / Equity Ratio | 0.00 | Excellent (Debt-Free) |
| EBITDA Margin | >40% | Strong |
| Net Profit Margin | ~30–32% | Strong |
| Revenue Growth (YoY FY24→25) | +23% | Strong |
| PAT Growth (YoY FY24→25) | +33% | Strong |
| EPS (FY25) | ₹9.3 | Healthy |
| Market Cap / Revenue | ~5.8× | Neutral |
| Fresh Issue Dilution | Zero | No Dilution |
VALUATION ANALYSIS & PEER COMPARISON
At the upper price band of ₹172 per share, CMPDI is valued at approximately ₹12,280 crore in market capitalization. Based on FY2025 EPS of ₹9.3, the implied P/E multiple is approximately 18.5× — a meaningful discount to both comparable listed PSU peers and the industry peer average of 22.6× cited in the RHP.
More notably, CMPDI's RoNW of 36.7% substantially exceeds both identified peers, suggesting the stock may be attractively priced relative to its capital efficiency and profitability metrics.
| Company | Market Cap | P/E | RoNW | Revenue (FY25) |
|---|---|---|---|---|
| CMPDI (IPO Price) | ~₹12,280 Cr | ~18.5× | 36.7% | ₹2,103 Cr |
| Engineers India Ltd (EIL) | ~₹10,500 Cr | ~22× | 23.5% | ~₹3,800 Cr |
| RITES Limited | ~₹9,200 Cr | ~23× | 15.5% | ~₹2,700 Cr |
| Industry Peer Avg (RHP) | — | 22.6× | — | — |
Note: Peer data sourced from company RHP (Basis for Offer Price section) using BSE closing prices as of March 5, 2026. CMPDI P/E based on FY25 EPS at upper band. All figures are approximate.
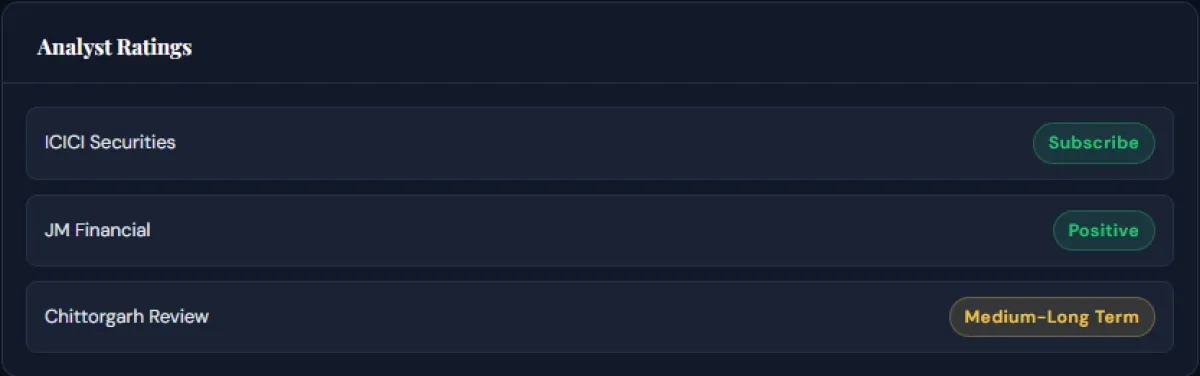
ICICI Securities has assigned a Subscribe rating, noting the IPO appears attractive at ~18× P/E given strong double-digit margins, healthy return ratios, debt-free balance sheet, and robust growth prospects.
It is worth noting that the issue is entirely an OFS — the company receives zero fresh capital. All ₹1,842 crore proceeds go to the selling shareholder (Coal India Limited).
KEY STRENGTHS
- Dominant 61% Market Sharein India's coal and mineral consultancy sector — deeply entrenched with no close competitor. This moat has been built over five decades of institutional knowledge.
- Strategic PSU Backing— Coal India and Ministry of Coal provide institutional stability, guaranteed order flow, government policy priority, and de-facto preferred vendor status.
- Exceptional Financials— Revenue CAGR of 23%, PAT CAGR of ~50%, EBITDA margins consistently above 40%, and a completely debt-free balance sheet (as of Dec 31, 2025).
- Valuation Discount to Peers— P/E of ~18.5× at IPO price vs industry average of 22.6×, while CMPDI's RoNW of 36.7% exceeds both comparable peers (EIL: 23.5%, RITES: 15.5%).
- Multidisciplinary Expertise— Comprehensive service offerings spanning geological exploration, mine planning, environmental management, geomatics, infrastructure engineering, and management systems under one roof.
- Advanced Infrastructure— One of India's largest exploratory drilling fleets; eight laboratories; seven regional institutes across key coal-producing states.
- Non-Coal Diversification Underway— Active diversification into UCG (Underground Coal Gasification), CBM (Coal Bed Methane), non-coal minerals (bauxite, copper, zinc, magnetite), and international consultancy.
- Government Energy Policy Tailwind— India's push for energy security, scientific mining, and mineral exploration aligns directly with CMPDI's service offerings.
- Consistent Dividend Payer— Follows Ministry of Finance guidelines for dividend payout, rewarding shareholders consistently.
KEY RISKS
- Extreme Customer Concentration— Coal India and its subsidiaries contributed 67.1% of FY25 revenues. Top 10 clients account for ~95% of revenues. Loss of any key client could materially impact financials.
- Near-Total Government Revenue Dependence— 97.8% of revenues derive from government entities/agencies. This exposes the company to regulatory risk, delayed receivables, and policy change sensitivity.
- Coal Sector Concentration— Geological exploration services alone contributed 46.2% of FY25 revenues. A structural decline in coal demand due to India's energy transition could impact long-term growth.
- Pure OFS — Zero Capital Inflow— All IPO proceeds go to Coal India (selling shareholder). No funds raised for business expansion, debt repayment, or operational improvement by the company itself.
- Government Policy & Funding Risk— Drilling and exploration activities significantly depend on funding from the Ministry of Coal and NMET (National Mineral Exploration Trust). Policy changes or funding delays could impact operations.
- Vendor Concentration in Exploration— Exploration activities depend on a limited number of vendors for services such as core drilling, geophysical logging, and borehole testing.
- Energy Transition Risk— India's long-term commitment to renewable energy and net-zero targets may gradually reduce the strategic importance of coal consultancy over a 10–15 year horizon.
- PSU Operational Constraints— As a government entity, CMPDI may face limitations in talent acquisition, salary flexibility, and operational agility compared to private sector peers.
IPO SUBSCRIPTION DATA (Day 1)
Subscription data as of end of Day 1 (March 20, 2026, 5:05 PM IST). Note: QIBs and large HNIs typically apply on the final day.
| Category | Shares Offered | Shares Bid | Subscription |
|---|---|---|---|
| Retail Individual Investors (RII) | 3,74,85,000 | ~3,74,85,000 × 0.10 | 0.10× |
| Non-Institutional Investors (NII) | 1,60,65,000 | ~1,60,65,000 × 0.05 | 0.05× |
| — S-HNI (Small) | — | — | 0.08× |
| — B-HNI (Large) | — | — | 0.03× |
| Qualified Institutional Buyers (QIB) | 5,35,50,000 | — | 0.00× |
| Overall | 7,97,89,500 | ~48,06,240 | 0.07× |
⚠ Day 1 subscription of PSU IPOs is typically low. QIBs and large HNIs conventionally wait until the final session on Day 3. The anchor round (₹470 Cr from 22 institutions including LIC, Goldman Sachs, Citigroup) signals strong institutional interest. Final subscription data will be available post March 24, 2026.
GRAY MARKET PREMIUM (GMP)
GMP data is unofficial and indicative only. It reflects informal market sentiment, not guaranteed listing price.
| Metric | Value |
|---|---|
| IPO Issue Price (Upper Band) | ₹172 |
| GMP — Peak (before opening) | ₹22–₹24 |
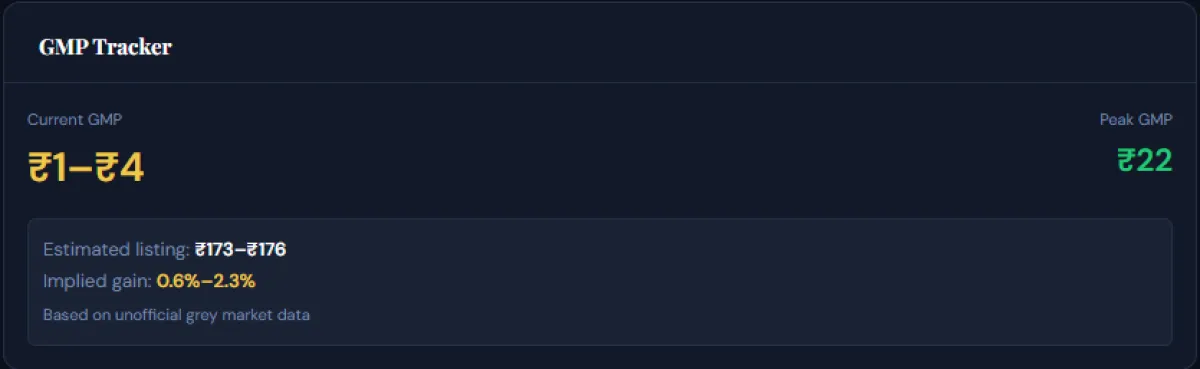
| GMP — Current (as of Mar 20, 2026) | ₹1–₹4 |
| Estimated Listing Price (GMP basis) | ₹173–₹176 |
| Estimated Listing Gain % | 0.58% – 2.3% |
| Unlisted Market Trade Price | ~₹173.5–₹176 |
GMP touched a high of ₹22 on March 17 but has cooled significantly by opening day, reflecting modest short-term listing gain expectations. The cooling GMP trend suggests the market is pricing this more as a long-term hold than a quick listing-gain trade. This is characteristic of large-cap PSU IPOs.
OBJECTS OF THE ISSUE
Since this IPO is a 100% Offer for Sale (OFS), the company (CMPDI) will not receive any proceeds from the issue. The entire net proceeds will be received by the Promoter Selling Shareholder — Coal India Limited.
| Purpose | Amount | % of Issue |
|---|---|---|
| Proceeds to Coal India Limited (Selling Shareholder) | ₹1,842.12 Cr | 100% |
| Proceeds to CMPDI (Company) | Nil | 0% |
The RHP states: "Our company expects that listing of the equity shares will enhance our visibility and brand image and provide liquidity and a public market for the equity shares in India." The listing creates a public market for shares but injects no capital into the operating company.
FINAL SUMMARY
Business Quality: CMPDI is a structurally strong business with a virtually unassailable competitive position — 61% market share, five decades of institutional knowledge, government backing, and a diversified yet specialized service portfolio. The company's role as the technical backbone of India's coal and mineral sector gives it a quasi-monopoly status in its niche.
Financial Strength: The financial profile is exceptional for a PSU. Revenue CAGR of 23%, PAT CAGR of ~50%, EBITDA margins consistently above 40%, zero debt, and strong return ratios (RoNW ~36.7%) — all indicators of a high-quality, capital-efficient business. The company generates strong free cash flows and pays regular dividends.
Valuation: At a P/E of ~18.5× (FY25 basis), the IPO appears attractively priced relative to comparable PSU consultancy peers (EIL at ~22×, RITES at ~23×) and the RHP-cited industry average of 22.6×. The superior return profile (RoNW significantly above peers) suggests a potential undervaluation relative to intrinsic quality.
Key Considerations: The 100% OFS nature means zero capital enters the business. Customer concentration (top 10 clients = ~95% revenues; CIL = ~67%) is a notable structural risk. Long-term energy transition risk is real, though medium-term coal dependency and India's mineral exploration push provide a clear runway for 5–10 years.
⚠ Disclaimer: This report is for informational and educational purposes only. It does not constitute investment advice. Investors should review the Red Herring Prospectus (RHP) available on the SEBI website and consult a SEBI-registered financial advisor before making any investment decision.
LISTING PROBABILITY ANALYSIS
Based on available GMP trends, Day 1 subscription levels, anchor investor quality, and sector/market sentiment, here is a probability assessment for various listing outcomes:
- Listing at Premium (>5% gain)Low – Medium
- Listing near IPO Price (±2%)Medium – High
- Listing at Discount (below issue price) - Low
| Factor | Indicator | Signal |
|---|---|---|
| Current GMP | ₹1–₹4 | Neutral |
| GMP Peak | ₹22–₹24 | Cooled significantly |
| Day 1 Subscription | 0.07× | Typical for PSU |
| Anchor Investor Quality | LIC, Goldman Sachs, Citigroup | Strong |
| Sector Momentum | Mining / PSU | Moderate |
| Valuation vs Peers | Discount (~18.5× vs 22.6×) | Favourable |
| ICICI Securities Rating | Subscribe | Positive |
| Listing Type | Long-term PSU Hold | Medium-Term Value |
The tepid GMP and slow Day 1 subscription are not unusual for large-cap PSU IPOs. Given high-quality anchors, attractive valuation versus peers, and strong fundamentals, the listing is more likely to be stable to marginally positive rather than a sharp premium or discount.
SOURCES & REFERENCES
SEBI — Company Red Herring Prospectus (RHP), certified by Deoki Bijay & Co., CA (March 12, 2026)
NSE India — Live subscription data and issue details
BSE India — Anchor investor circular, allotment details
Screener.in — Financial ratios: P/E, ROCE, EPS, RoNW, Net Worth
IPO Watch — GMP data, subscription status, financial summary
Chittorgarh.com — IPO details and review
MyInvestmentIdeas.com — Detailed RHP-sourced analysis
JM Financial — Financial analysis and CAGR data
Upstox / Business Media — Day 1 live subscription updates
Goodreturns — ICICI Securities Subscribe rating and analysis
KEY DATES
| Anchor Round | Mar 18, 2026 |
|---|---|
| IPO Opens | Mar 20, 2026 |
| IPO Closes | Mar 24, 2026 |
| Allotment | Mar 25, 2026 |
| Refund Initiation | Mar 27, 2026 |
| Listing Date | Mar 30, 2026 |
| Exchange | BSE & NSE |
Financial & Regulatory Disclaimer
InvesTalks provides stock market analysis, equity research, and financial content strictly for educational and informational purposes only. We are not a SEBI-registered investment advisor or portfolio manager. Market investments are subject to market risks. Always perform your own research or consult a certified SEBI-registered financial advisor before making buy/sell decisions.
Admin
Equity Research & Financial AnalysisCurated by the InvesTalks financial analysis team. Dedicated to providing disciplined stock market insights, technical chart evaluations, and long-term investor education.
 Market News & Outlook
Login to comment.